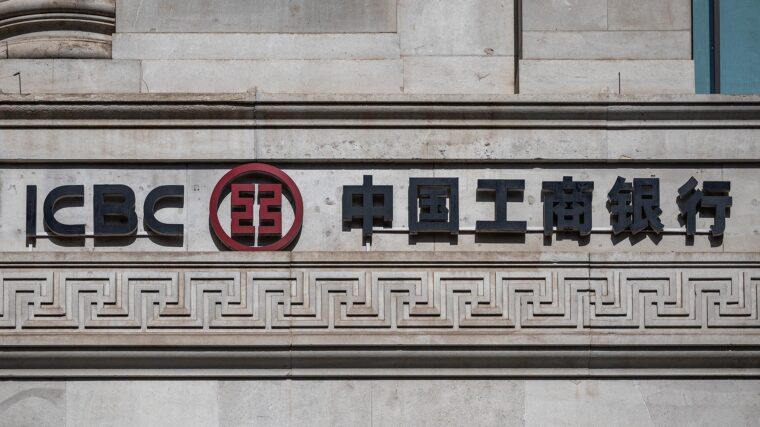
In the heart of London’s financial district, tucked between the Bank of England headquarters and London Bridge, is one of the world’s most influential institutions. The majestic neoclassical building is hard to miss, but few passersby would recognize the ancient coin-inspired logo of the Industrial and Commercial Bank of China.
This outpost of the biggest bank in the world has grown over three decades to hold tens of billions of dollars in assets, expanding rapidly as China has ascended on the world stage. And yet its daily operations remain highly secretive.
For the first time, a trove of confidential records reviewed by the International Consortium of Investigative Journalists offers a window onto the inner workings and decision-making of ICBC, a vital cog in China’s global geopolitical ambitions. The records reveal that the state-owned bank has used London as a financing hub for companies linked to sanctioned Russian and Belarusian business owners, autocrats publicly accused of corruption and China’s political establishment.
As part of China Capital, ICIJ found that at times the bank’s Beijing headquarters directed bank officers overseas to pursue explicitly political objectives for its majority shareholder, the Chinese state — to cement alliances, acquire natural resources and expand control over communications, energy and transportation infrastructure around the world. While doing so, ICBC breached some of its own anti-money laundering and sanctions policies, the investigation found.
ICIJ examined 4.8 million ICBC records in collaboration with 23 media partners. The files, in English and Chinese, come from the confidential archives of ICBC’s London branch and a separate subsidiary at the same address, and are dated between 2005 and 2024. They include reports marked as trade secrets; internal emails; confidential dossiers and lists with details on more than 4,000 corporate clients; meeting minutes; suspicious transactions logs; and directives from the bank’s Communist Party committee, an internal cell that facilitates party activities and advances government policies.
China Capital shows how ICBC London routinely financed companies with opaque financial flows and murky corporate ownership, justifying the deals as part of its support for the government’s top priorities: the massive infrastructure investment plan known as the Belt and Road Initiative and the industrial policy Made in China 2025. The bank’s risky practices often sparked internal misgivings and recriminations, the records show.
“There is very little appetite to offboard high financial crime risk business,” a money laundering reporting officer noted in an internal memo in 2019.
China Capital reveals that ICBC offered services to clients that were shunned by Western lenders for failing to stem corruption or cut ties with sanctioned owners or partners. Among its top clients: Russian and other companies crucial to sustain Moscow’s military operations.
Those included the Russian mining giant Norilsk Nickel, also known as Nornickel, held up by President Vladimir Putin as a symbol of resistance despite the difficulties caused by the Western sanctions. In 2024, ICBC London and other overseas branches considered providing loans in Chinese currency and other financial services to Nornickel — a longtime client controlled by Putin allies — at a time when the U.K. and the U.S. had banned imports of Russian nickel in an effort to starve the Kremlin’s war machine. As other international banks wavered, ICBC remained a reliable partner, the records show. Nornickel’s minerals are vital to China’s booming electric vehicle and battery industries.
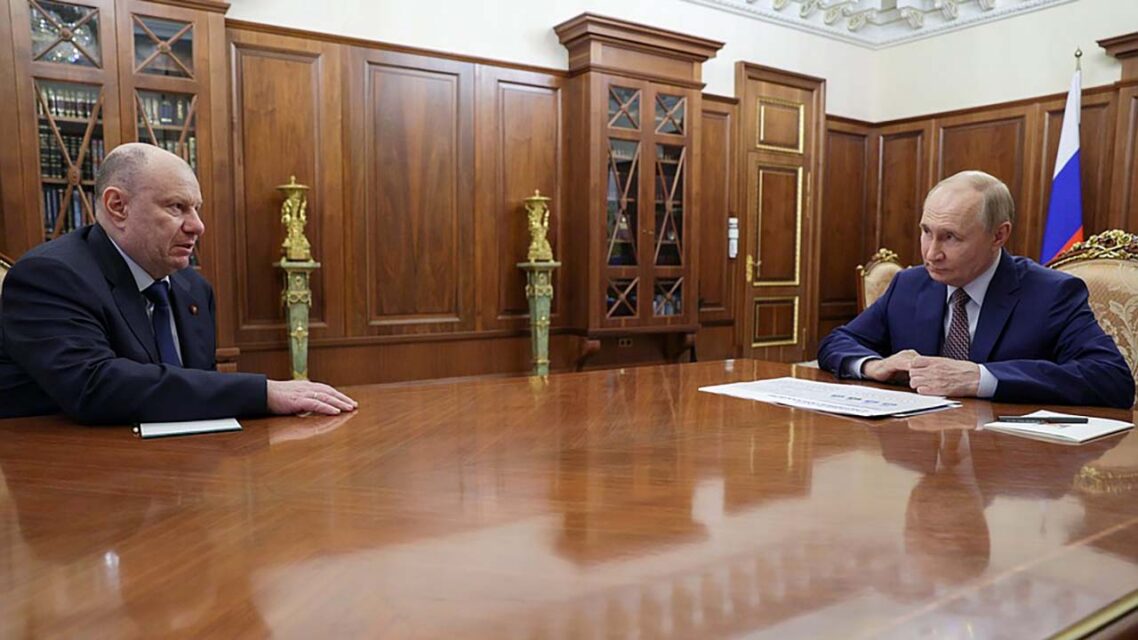
Norilsk Nickel CEO Vladimir Potanin, left, meeting with Russian President Vladimir Putin in October 2025. Image: via Kremlin.ru
ICBC was one of the few foreign banks that actually increased exposure to Russia after Russia’s full-scale invasion of Ukraine. Between 2022 and 2023, ICBC more than doubled its gross revenue in Russia and earned around $370 million in 2024, according to the latest available figures analyzed by the Kyiv School of Economics.
While regulators in the U.S., Canada and Luxembourg have fined the bank’s local units for violating rules to prevent financial crimes, including those to combat sanctions evasion, the confidential records reveal that about a dozen other countries had expressed concerns about similar flaws at ICBC’s overseas entities. The bank’s executives were also aware of compliance failures at its London operations, the records show.
Through a spokesperson, the Chinese government said it rejects any “false narratives” of “opaque lending.” A representative for the Embassy in Zambia told ICIJ in a statement that China’s overseas financing “strictly” follows market rules and international norms and “never … seeks political interests.”
China Capital exposes how ICBC helps Beijing to pursue profit and power, ignoring international standards when the occasion suits. ICBC did not respond to ICIJ’s repeated requests for comment.
Christopher Walker, vice president at the Center for European Policy Analysis, said in an interview with ICIJ that China’s banks provide badly needed capital “desired around the world” — but with less regard for conventional banking standards, transparency and accountability. “What is typically missing is both the information about what can accompany those resources — which is censorship, surveillance, forms of corruption, secrecy, wrapped around such financing — and often forms of elite capture, certainly in more vulnerable settings,” Walker said. “Authoritarian capital, in the end, is quite corrosive capital.”
Serving shareholders and the state
ICBC was founded in 1984 to take over the commercial banking operations of China’s central bank. While ICBC is listed on the Hong Kong and Shanghai stock exchanges, its majority shareholders are China’s Finance Ministry and state-owned entities.
ICBC is the biggest of China’s four state-controlled institutions that present themselves as commercial banks. But unlike their international counterparts, ICBC and the others have a dual mandate of maximizing profits and serving the economic interests of the party-state.
According to James Stent, a former banker who was on the board of two Chinese lenders, ICBC has to “please two masters”: the party and the shareholders. “The government guides banks in areas of the economy it wishes them to lend into, to support the government’s five-year plan,” Stent told ICIJ. “At the same time, it uses the bottom-line profit of the banks to keep score, so to speak, on the competence of the management team.”
ICBC has been a major force in China’s global expansion strategy, establishing 410 subsidiaries and branches in 49 countries and regions by the end of 2025. With more than $8 trillion in assets, it is the biggest bank in the world by asset size.
Top 10 global banks by assets, 2026
S&P
Data: via S&P. Assets as of Dec. 31, 2025.
This year marks 30 years since ICBC established its presence in the U.K. From the century-old building on London’s King William Street, ICBC now runs a branch of the Chinese parent and a separate ICBC subsidiary that has provided cash accounts to a range of retail clients, including Chinese diplomats and academics living in the U.K. and some British officials. Both entities are regulated by Britain’s main financial services watchdog, the Financial Conduct Authority.
The rapid growth of ICBC London’s operations over the last decade has roughly coincided with President Xi Jinping’s ambitious economic policies: the Belt and Road Initiative, to build and invest in massive infrastructure projects expanding China’s market access — and influence — around the world; and Made in China 2025, to transform China into a high-tech superpower by acquiring cutting-edge technology and dominating global supply chains.
ICBC in the U.K. became an important conduit to achieve those goals, financing Chinese investments in key infrastructure projects and extending loans to foreign state entities to shore up Beijing’s political alliances. But while the bank grew its portfolio of clients, it lacked adequate policies to vet politically exposed clients — prominent people more susceptible to bribery or corruption. And some managers viewed standard rules designed to prevent financial crimes as a hurdle to the business, the records show.
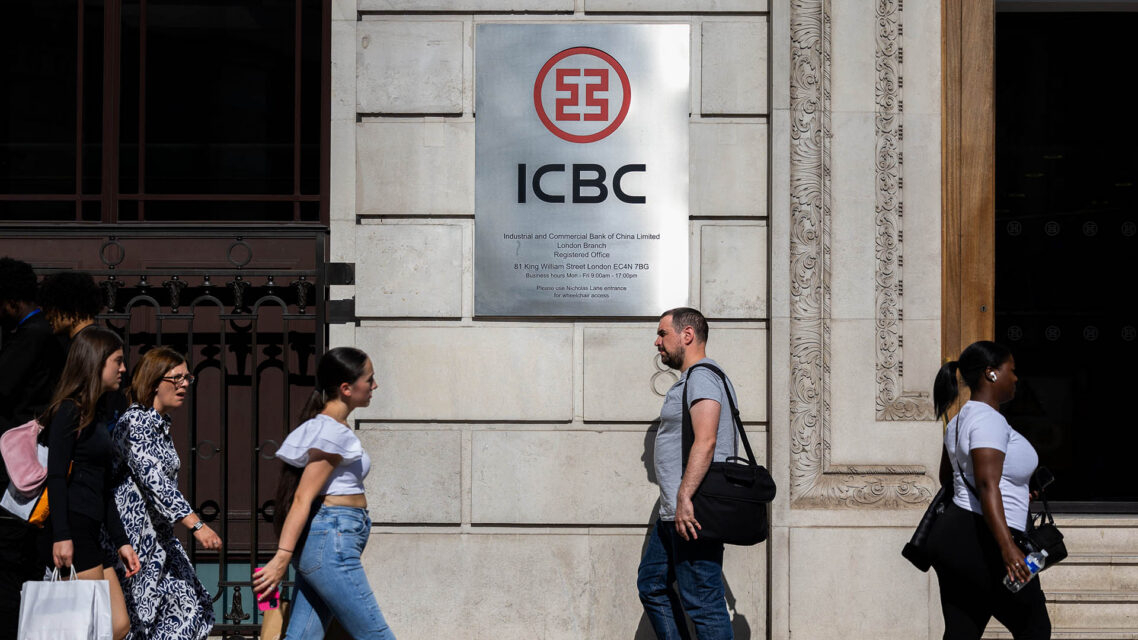
Industrial and Commercial Bank of China Limited’s London headquarters. Image: May James/SOPA Images/LightRocket via Getty Images
The autocrat’s daughters
In early 2016, two sisters named Arzu and Leyla Aliyeva approached ICBC London to open an account for Pasha Bank, a financial institution they co-owned alongside their grandfather, Arif Pashayev. The women, ages 29 and 31 at the time, listed jobs in the media industry as their source of wealth, but a detail in their résumés stood out: The Aliyevas are the daughters of Ilham Aliyev, Azerbaijan’s authoritarian ruler since 2003 and the subject of repeated investigations into corruption allegations. Pashayev is his father-in-law.
Confidential emails show that ICBC analysts understood early on that the clients were risky but “overlooked” evidence of possible corruption exposed in a number of media reports. ICIJ’s 2013 Secrecy for Sale investigation had revealed the sisters’ links to offshore companies that benefited from building contracts worth billions amid a massive construction spree by Aliyev. And as the bank assessed whether to take on the Aliyevas’ bank as a client, ICIJ’s Panama Papers investigation revealed that the women indirectly controlled companies with interests in Azerbaijan’s telecommunications, construction, mining, oil and gas sectors. The investigation also uncovered yet another piece of their vast real estate portfolio: a London property worth millions that they owned through a web of secretive shell companies, a tactic often used to hide the origins of funds. The Aliyevs have previously denied wrongdoing.
ICBC records show that bank officers brushed off concerns about whether the prospective clients’ funds had been legally obtained. In a memo, an ICBC analyst observed that scrutiny of the sisters’ Pasha Bank was unlikely because the judiciary and law enforcement were under the control of the Azerbaijani government — led by their father. “The entity and the [ultimate beneficial owners] are not likely to be investigated,” the memo said. So in 2017, ICBC London accepted Pasha Bank as a client.
But in 2021, about two years after British authorities investigated an Aliyev business associate and his wife suspected of buying U.K. assets with illicit funds, ICBC London finally expressed concern about Pasha Bank. An officer noted: “due to ambiguity over the source of funds, one cannot rule out that the funds deposited with ICBC London could have been potentially contaminated by the proceeds of crime.” Pasha Bank didn’t respond to ICIJ’s requests for comment.
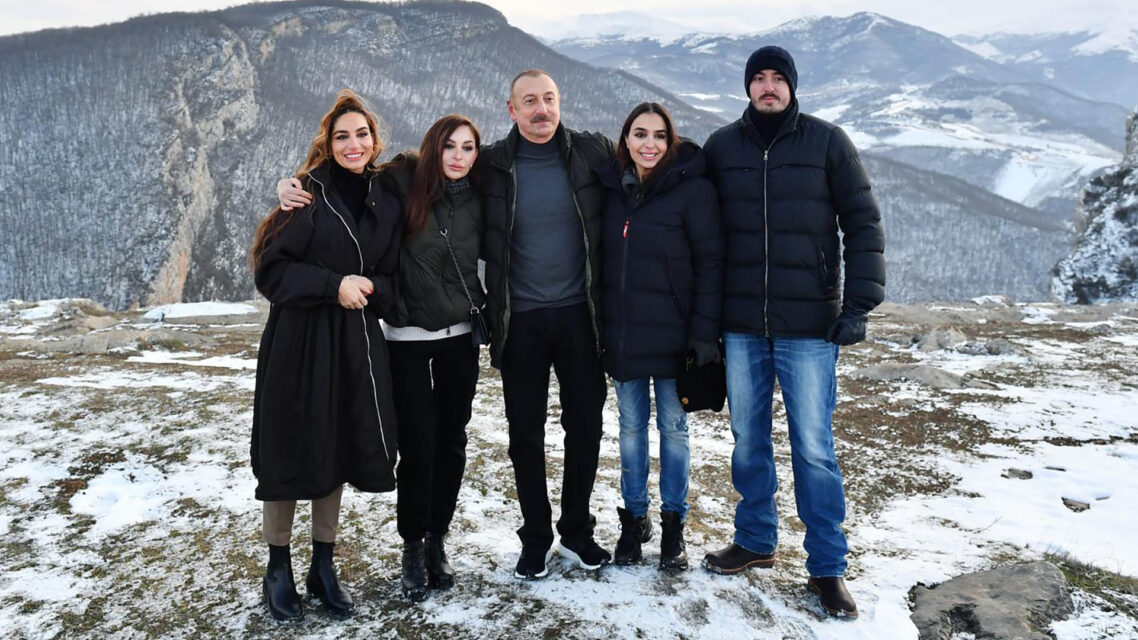
Azerbaijani President Ilham Aliyev, center, with his daughter Arzu Aliyeva, wife Mihriban Aliyeva, daughter Leyla Aliyeva and son Haydar Aliyev in Shusha, Azerbaijan in 2021. Image: via president.az
ICBC decided to end its relationship with Pasha Bank. But it took its time. Senior managers pushed back against some bank officers’ suggestions to immediately drop the client and agreed to wait until Pasha Bank’s deposits — then worth $24 million — matured a few months later.
At the same time, ICBC London kept another Aliyev-linked company as a client: Azerbaijan’s state oil concern, Socar. The Western Asian nation is a key transportation hub and has received more than $900 million in Chinese investments since 1995, according to estimates by the Azerbaijani government. In exchange, the Aliyev government has supported a regional security partnership led by China and Russia, as well as Beijing’s positions at the United Nations and its controversial territorial claims over Taiwan.
Socar is a key source of public funding for Azerbaijan. Past media investigations have revealed how the president’s family and friends used the company to register a luxury mansion in London and to vacation on two company yachts worth $59 million. A German government probe also found that Socar representatives made an illegal donation to a political party, and U.S. prosecutors alleged in an indictment against a member of Congress — later dropped after President Donald Trump pardoned him — that Socar had paid him to advance Azerbaijan’s interests.
In 2021, ICBC London agreed to lend about $90 million to its longtime client Socar to help it refinance an old loan. The bankers dismissed an outside compliance firm’s warnings that the company was opaque and mired in corruption allegations, the records show.
ICBC officers acknowledged Socar’s lack of transparency and accountability but concluded that the client was simply too important for Beijing: “SOCAR is a strategically important client for ICBC in view of supporting China’s 2013 One-Belt One-Road policy aimed at creating infrastructure and establishing links among the Eurasian countries.”
https://www.icij.org/investigations/china-capital/huawei-icbc-banking-us-court-beijing-london/
HUAWEI Chinese bank helped Huawei spirit $1B out of London days after US indictment of the tech giant Sep 14, 2026
https://www.icij.org/investigations/china-capital/about-china-capital-investigation-icbc/
Asia-Pacific About the China Capital investigation Sep 14, 2026
https://www.icij.org/investigations/china-capital/zhang-hongli-icbc-executive-corruption-employee-misconduct/
CORRUPTION ICBC promoted corrupt executive, ignored employee misconduct as it pursued global expansion Sep 14, 2026
Recommended reading HUAWEI Chinese bank helped Huawei spirit $1B out of London days after US indictment of the tech giant Sep 14, 2026 Asia-Pacific About the China Capital investigation Sep 14, 2026 CORRUPTION ICBC promoted corrupt executive, ignored employee misconduct as it pursued global expansion Sep 14, 2026
>
About a year after the payments, the sheikh’s father, Sheikh Jaber al-Mubarak al-Sabah, resigned as prime minister amid allegations of embezzlement of millions of dollars in military aid funds. Months later, Kuwaiti prosecutors arrested the son, accusing him and other accomplices of laundering more than $1 billion linked to the plundering of Malaysia’s sovereign wealth fund — part of a global criminal case that involved influential politicians, pop stars and fraudulent financiers.
A suspicious-activity report months after his arrest revealed alarming new details about the transactions. In the report dated early 2021, an officer at ICBC London wrote she suspected that “the 2 aforementioned payments made to UK Law Firms were to launder the proceeds of Sheikh Sabah’s involvement in the 1MDB scandal, by investing them in UK property.” A Kuwaiti court later sentenced him to 10 years in prison.
Sarah Beth Felix, an anti-money laundering and sanctions expert who also trains law enforcement, told ICIJ that the sheikh should have been classified as a politically exposed person, which would have prompted additional checks on large transactions well before the banker filed the suspicious-activity report.
“If they would have designated him correctly, the transactions would have triggered some kind of alert,” she said.
The FCA said it doesn’t comment on specific companies. “Fighting financial crime is a priority for the FCA,” a spokesperson for the agency told ICIJ in an email. “We look carefully at all issues raised with us,” he said.
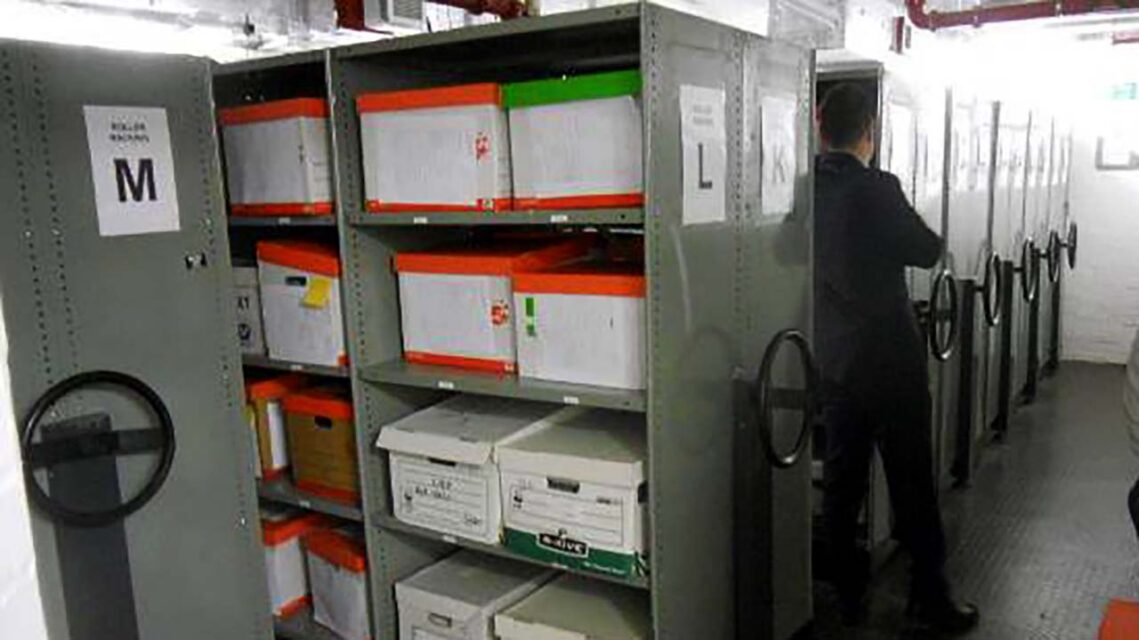
A photo from inside the ICBC London offices. Image: via China Capital confidential files
Banking kleptocrats
ICBC repeatedly dismissed allegations of corruption and other crimes against company executives in countries governed by autocratic leaders, including oil-rich Angola under longtime dictator José Eduardo dos Santos.
When convenient for Beijing, the records show, the bankers would willingly serve state companies — even those that were not transparent about their financial flows and controlled by governments that, in the words of one ICBC banker, were “clearly kleptocracies.”
Ben Cormier, a senior lecturer of international political economy at the University of Strathclyde in Scotland, said part of Chinese lenders’ appeal for corrupt governments is that the Chinese government is not especially interested in either transparency or accountability. “The lack of accountability is a selling point,” he said in an interview with ICIJ.
ICBC London helped the bank’s headquarters dole out more than $2.5 billion in loans to Angola’s state-owned oil and gas company, Sonangol Group, while it was controlled by cronies of dos Santos, another subject of widely publicized corruption allegations. Internal memos about a 2010 loan illustrate China’s leverage as Angola’s largest foreign creditor, requiring Sonangol to both sell its oil to China and use the loan proceeds to hire Chinese construction companies.
The bank’s partnership with Sonangol continued well after ICIJ’s 2020 Luanda Leaks investigation revealed that Sonangol’s U.K. subsidiary — ICBC London’s direct client — was involved in the payment of about $58 million to a Dubai consulting company controlled by a friend of Isabel dos Santos, the president’s daughter and head of Sonangol between 2016 and 2017.
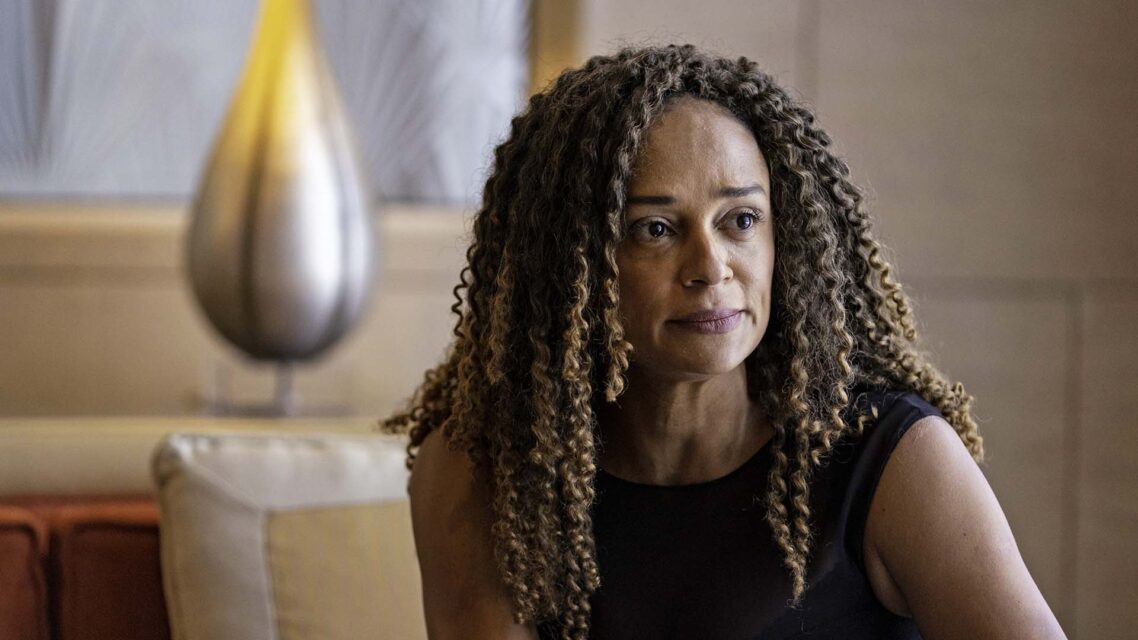
Isabel dos Santos, Angolan businesswoman and daughter of former Angolan President José Eduardo dos Santos. Image: Christopher Pike/Bloomberg via Getty Images
Internal memos dated 2021 show that ICBC analysts dismissed the findings and said any criticism of the Angolan president’s daughter was “motivated to some degree by chauvinistic interest.” Isabel dos Santos was later sanctioned by the U.S. and the U.K. governments, and charged by Angolan prosecutors for causing state losses of around $219 million while she was head of Sonangol. She has repeatedly denied wrongdoing. Sonangol did not reply to ICIJ’s comment requests.
One of those ICBC memos provided a simple argument for why the bank would continue banking with the oil company: “Angola is a belt and road partner of China and an emerging markets client we have supported for over a decade from ICBC London.”
ICBC's presence outside of China
ICBC 2025 Annual Report.
Source: ICBC 2025 Annual Report.
Overlooking sanctions risk in Belarus
China’s backing of authoritarian regimes and allies has long been on display in Belarus, where dictator Alexander Lukashenko has ruled for more than three decades, brutally repressing any dissent.
In early 2018, ICBC London became the overseas banking hub for Chinese construction giant Zoomlion Heavy Industry Science and Technology. Zoomlion’s U.K. subsidiary — known as Zoomlion Powermole Ltd. — was the majority shareholder in a joint venture with a Belarusian state concern that invested in an industrial park near the Minsk airport. The park included a production hub for automated cranes and other heavy vehicles. Back when he was China’s vice president, Xi had personally promoted the “landmark” project for his Belt and Road Initiative, alongside Lukashenko.
Zoomlion used its U.K. subsidiary’s ICBC London account to pay for the lease of state land and fund the park development.
In the summer of 2020, Western governments imposed sanctions on some Belarusian entities after Belarusian authorities arrested more than 7,000 protesters and tortured hundreds who accused the government of rigging the elections that crowned Lukashenko president for the sixth time. At least three people died, according to human rights advocates. Even so, China and Russia pledged to support Lukashenko’s violent regime.
As Lukashenko’s government increased repression against regime critics, and later emerged as a key supporter of Russia’s military aggression, the European Union and its allies expanded the sanctions package. New sanctions targeted Zoomlion’s Belarusian partner in the joint venture, Minsk Automobile Plant, or MAZ, which was described by Lukashenko himself as “one of the most important industrial enterprises of the country,” according to EU sanctions records. MAZ also supplied the Russian occupation forces in Ukraine with machinery, including trucks equipped with anti-drone technology. While the U.K. didn’t blacklist MAZ, it imposed restrictions on the supply of dual military-civilian goods and other technology to Belarus.
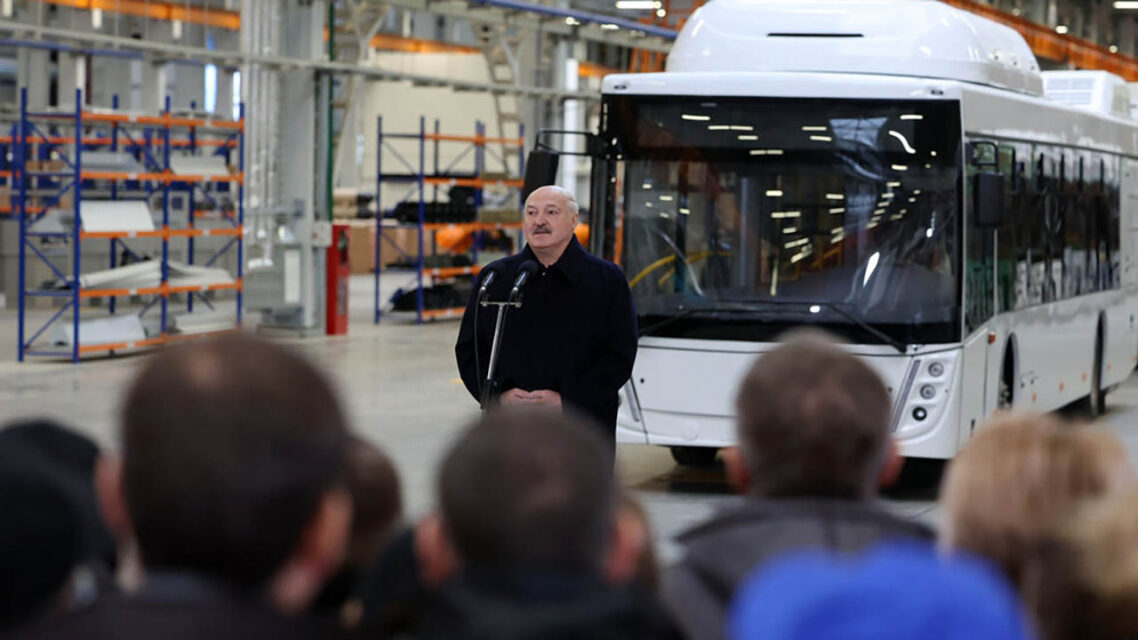
Belarusian President Alexander Lukashenko at the Minsk Automobile Plant, known as MAZ, in January 2025. Image: via president.gov.by
The sanctions didn’t seem to worry ICBC London, the records show. In 2021, Zoomlion wired more than $7 million to the Belarusian joint venture as part of its investment in the industrial park.
ICBC London officers acknowledged in internal emails that the joint venture was involved in the production of heavy machinery that could be considered dual-use technology. Despite MAZ’s role in the company, ICBC officials found “no sanction concern,” saying the Belarusian firm had only a 3.03% stake in the venture.
Still, documents obtained by ICIJ’s media partners at the Belarusian Investigative Center show that Zoomlion and MAZ later worked on a plan to “circumvent” trade restrictions.
After the U.S. sanctioned MAZ in 2023, identifying it as a “significant source of revenue” for the Lukashenko regime, the Belarusian firm left the joint venture. It eventually signed a deal with Zoomlion that would allow MAZ to supply truck chassis to Zoomlion through an unsanctioned third party. MAZ did not reply to requests for comment. It is not clear if the plan was executed.
Procurement records uncovered by the Belarusian Investigative Center show that last year Zoomlion’s Belarusian firm obtained a no-bid contract to supply three truck cranes, each capable of lifting more than 27 tons, to the Belarusian military, which closely cooperates with Russian forces.
A Zoomlion spokesperson told ICIJ in an email that the company and its subsidiaries “manufacture and distribute civilian construction equipment” and strictly comply with the laws and regulations of the jurisdictions where they operate. Zoomlion declined to comment on specific transactions and customers citing “commercial confidentiality obligations.”
t Union. He was once accused by a business rival in a London court case of bribery and ordering the murder of a bank executive — allegations he denied. A leaked U.S. diplomatic cable placed Deripaska “among the 2-3 oligarchs Putin turns to on a regular basis.”
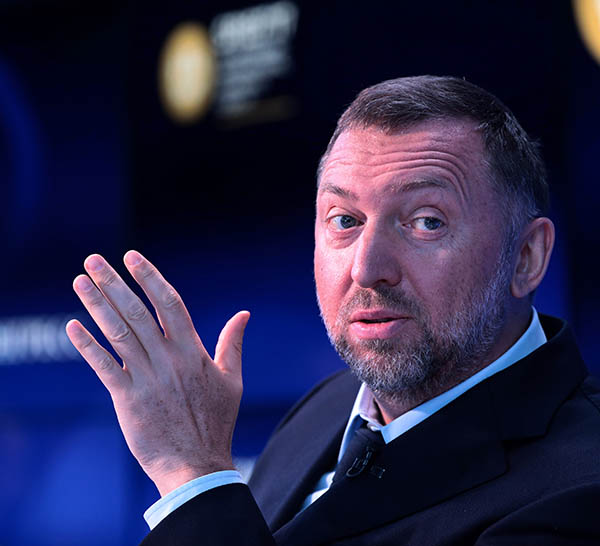
Russian billionaire Oleg Deripaska. Image: Simon Dawson/Bloomberg via Getty Images
In 2017, as part of an agreement allowing borrowing of up to $2.5 billion, ICBC’s Beijing office used the London branch to provide $105 million to the Russian mining giant Nornickel, in which, the bank records say, Deripaska indirectly held a 13% stake. The following year, the U.S. government sanctioned Deripaska for allegedly benefiting from Russia’s “malign activity around the globe” and froze his U.S. assets, including his New York and Washington, D.C., mansions.
When months later an ICBC London anti-money laundering officer noticed that Deripaska had, in fact, been sanctioned, he warned other bank officers that the branch was in breach of its own sanctions policy. The bankers, though, decided to make an exception for Nornickel, reasoning that Deripaska was only a minority shareholder who didn’t appear to control day-to-day operations, ICBC records show. Deripaska said on social media at the time that he denied any wrongdoing and that the sanctions were politically motivated.
In an internal report, ICBC Beijing officers suggested that Nornickel was simply too important for the bank to sever the relationship. Nornickel itself has not been sanctioned. “ICBC Group has long-term relationship with the company,” an officer wrote. The report also noted that the London branch shouldn’t question the decision from headquarters: “Maintaining the good and cooperative relationship with head office is helpful for us to develop more business with [head office] together.”
ICBC would commit to lend an additional $200 million to Nornickel in 2020, as part of a loan with 21 other banks, including three other Chinese state banks, JPMorgan Chase, UniCredit and other European and Asian financial giants. (Nornickel and JPMorgan did not respond to ICIJ’s questions. UniCredit declined to comment on the matter.) ICBC London later changed its internal policy so that it could bank with clients that are less than 10% owned by sanctioned entities or individuals.
But Russia’s invasion of Ukraine in 2022 triggered a new round of Western sanctions and, in response, strict capital controls issued by the Kremlin. This led to a six-month stalemate for Nornickel when it had to start paying back the loan, records show. In 2023, Nornickel resorted to asking Moscow for special permission to pay the banks in foreign currency, which was granted. However, it was a sign that many international banks would not be an option for future loans, and Nornickel executives traveled to China, where they visited 12 potential new lenders, according to the records.
A view of the non-operating Nikel smelter, owned by the Russian mining giant Norilsk Nickel, also known as Nornickel, in the town of Nikel in the Murmansk region. Image: Kirill Kudryavtsev/AFP via Getty Images
For ICBC it was an opportunity. Its branches in Moscow and Shanghai already provided “substantial” services to the mining giant, including foreign exchange, deposits and cash management, according to a 2024 internal memo. The bank considered working on a new credit line in China’s own currency, the renminbi, as a way around U.S. dollar financing.
Meanwhile, ICBC London officers weighed the risks of retaining the Russian client and applauded Nornickel’s idea to build a smelting plant in China and label its products Chinese to avoid potential sanctions.
An officer from the bank’s Financial Crime Prevention Unit reasoned in an internal memo: “This is because it is harder to sanction a Chinese good made in China.”
In the summer of 2024, ICBC London’s chief risk officer prepared a presentation with graphics in traffic light colors — green, yellow, red, for low, medium and high risk in all areas, including financial, geopolitics and security. The presentation warned that the bank was facing difficult times. U.S.-China relations were strained, “geopolitical risk” was high and Beijing’s support of the Kremlin didn’t help.
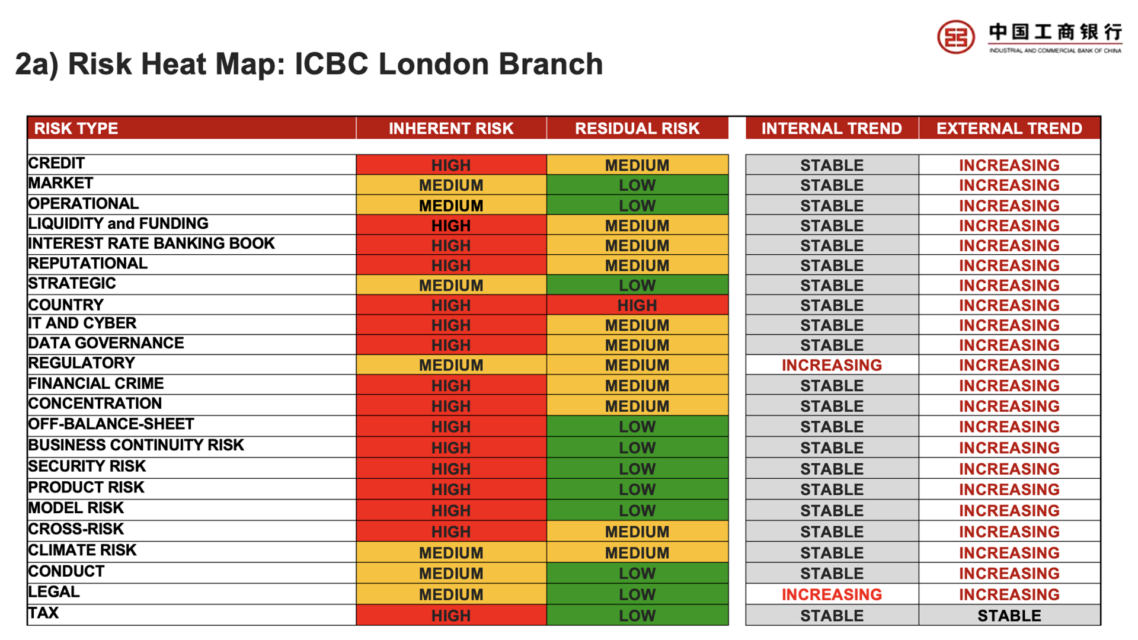
A traffic light-coded risk heat map from a presentation at ICBC London. Image: via China Capital confidential files
“China’s relations with Russia are very good and this causes friction with the West,” the officer wrote.
Headquarters was urging all the subsidiaries and branches to form a united front, with the whole bank acting as one. The presentation quoted the bank’s motto: “One branch, one policy,” a reference to Xi’s famous mantra, “One Belt, One Road.” Unified under the guidance of ICBC’s Beijing headquarters, the presentation said the bank could manage “any likely scenario.”
Contributing reporters: Denise Ajiri, Agustin Armendariz, Kathleen Cahill, Jelena Cosic, Jesús Escudero, Miguel Fiandor Gutiérrez, Micah Reddy, Delphine Reuter, Fergus Shiel, Dean Starkman, Angie Wu (ICIJ), Gloria Riva (L’Espresso), Sviatlana Yatskova (Belarusian Investigative Center).